
Why PET innovation also demands adhesive innovation
As PET bottles incorporate more recycled content, become lighter and adopt label constructions, the adhesive securing the label must perform
As PET bottles incorporate more recycled content, become lighter and adopt label constructions, the adhesive securing the label must perform
Is the overlap between policy, circularity, and renewable materials a sweet spot for packaging innovation – and how do we make
In this edition of The Brief, we’re trying something a bit different – I’m reflecting on the stories we’


Is the overlap between policy, circularity, and renewable materials a sweet spot for packaging innovation – and how do we make the most of it?
In this edition of our ‘In Conversation With…’ series, Jukka-Pekka Rantakokko, Director, Public Affairs at UPM, talks EU regulation, fibre-based trends, and how UPM’s recyclable and renewable packaging portfolio responds to it all.
Jukka-Pekka Rantakokko, Director, Public Affairs at UPM
The Packaging and Packaging Waste Regulation, or PPWR, sets a clear direction: Packaging placed on the EU market must become recyclable, while unnecessary packaging and reliance on virgin fossil resources must decrease. More fundamentally, PPWR should not be a debate about recycled versus bio-based materials. It should be a debate about how Europe progressively replaces fossil carbon in packaging.
Recycling remains essential, but renewable carbon also has an important role to play where virgin material demand remains necessary. This aligns with UPM’s approach – using renewable and recycled resources efficiently in high-performance packaging and labelling materials which are designed for established recycling systems. Regulation does not replace innovation, but it defines the conditions under which it must succeed.
Regulatory certainty matters at two stages. First, companies need clarity on the technical requirements their solutions must meet. Product development, production investments and brand owners’ material choices are made years in advance, so uncertainty about future performance and recyclability criteria can delay decisions and make it harder to scale promising innovations.
PPWR illustrates this challenge. Although the regulation has applied since August 2026, the detailed legislation needed for the actual implementation will continue to be developed over the next two to three years. The direction is clear, yet the design-for-recycling criteria and performance grades that will apply from 2030 are still being defined.
Policymakers should finalize technically robust rules early and provide realistic lead times. Otherwise, companies may postpone investment or commit to solutions based on requirements that could later change.
The second dimension is market certainty: Companies need confidence that demand will exist once renewable solutions are ready. Europe already uses recycled-content targets to create markets; carefully designed demand-pull measures could likewise help renewable solutions compete with established fossil-based materials and reach industrial scale.
Recent independent analysis suggests that the principal barrier is no longer technology readiness, but the absence of predictable demand signals capable of supporting investment and deployment at scale. These approaches should be complementary, because a circular economy ultimately needs both recycled and renewable carbon.
The question is therefore not whether Europe will continue to need virgin materials, but whether those materials remain fossil-based or increasingly become renewable.
The main challenge is whether detailed rules recognize how different materials and recycling systems work in practice.
Under the PPWR, the resulting criteria should be material-specific and based on validated evidence from relevant collection, sorting and industrial recycling processes, rather than on theoretical material-purity thresholds or assumptions about individual packaging components.
Businesses also need to collaborate across the value chain and design packaging as a complete system. Early dialogue between industry, recyclers and policymakers is critical.
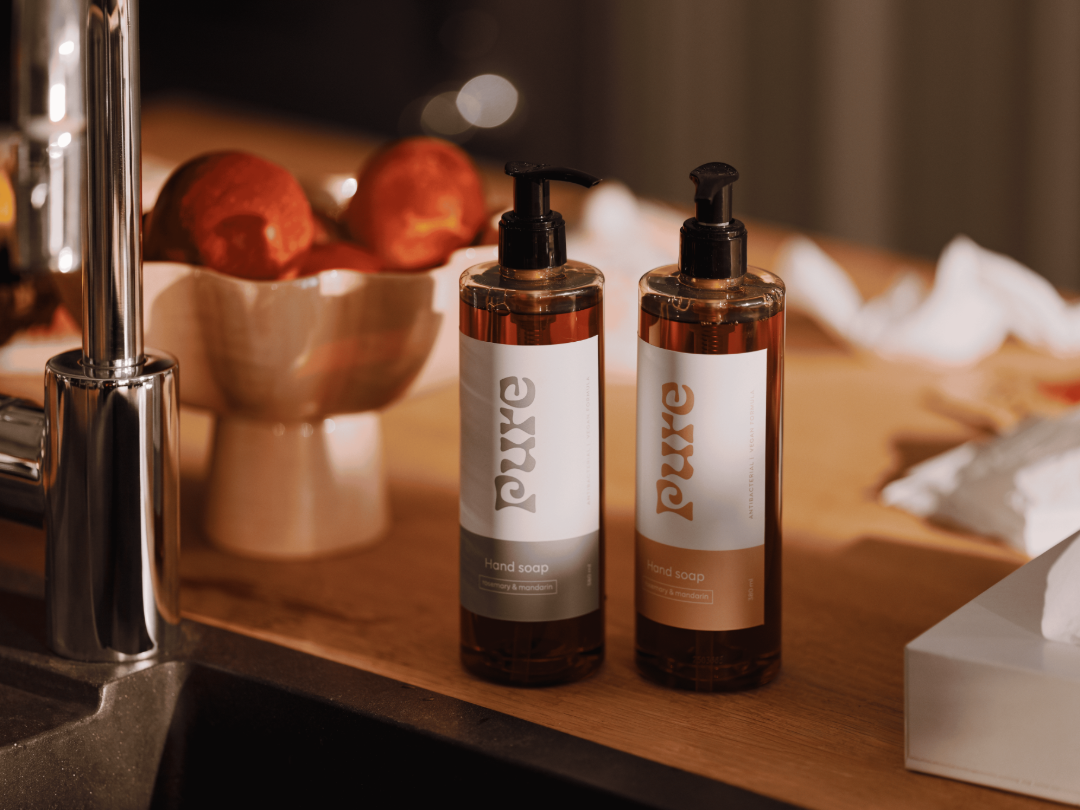
UPM’s strength lies in our ability to contribute at multiple points across the packaging value chain. We supply pulp for fibre-based packaging; packaging papers for food and non-food applications; paper and film label materials, including solutions designed to support recycling and reuse; renewable, wood-based feedstocks; and biochemicals for applications such as PET packaging.
Across this portfolio, the objective is the same: help customers reduce reliance on virgin fossil resources, improve recyclability and use materials efficiently without compromising product protection, safety or performance. No single material is right for every application, so material performance and sustainability start with choosing the right solution for the job.
Ultimately, our objective is not simply to replace one material with another. It is to help reduce dependence on fossil carbon through renewable and recyclable solutions that can work within existing value chains and recycling systems.
A good example is the packaging developed by UPM Specialty Materials and EvoPak for Walkers Chocolates, which replaces plastic wrappers with recyclable paper packaging. The new wrapper combines UPM’s barrier base paper with EvoPak’s special coating, making it suitable for chocolate and other demanding end uses. It keeps chocolate fresh and meets demanding quality standards.
The packaging is designed for recycling in existing fibre recycling systems and supports a circular economy. Products from Walkers Chocolates that are packaged using this solution are already available at multiple UK retailers and in international markets.
UPM’s next priority is to expand the range of applications in which renewable and recyclable materials meet demanding performance requirements. That means co-creating flexible fibre-based packaging with tailored barriers, labels compatible with different recycling streams, and wood-based biochemicals that can defossilize established material value chains.
The innovations already exist. The next challenge is ensuring they can scale. That requires clear and technology-neutral regulation, sufficient recycling infrastructure and predictable market demand.
Europe has spent many years supporting innovation; the next step is creating the lead markets that allow renewable and recyclable solutions to achieve industrial scale. Done correctly, this can strengthen European competitiveness, reduce dependence on imported fossil resources and accelerate the transition toward a more circular and resilient packaging system.
Click here to learn more about UPM's packaging and labelling portfolio.

As PET bottles incorporate more recycled content, become lighter and adopt label constructions, the adhesive securing the label must perform

In our latest Spotlight, we learn how Coexpan and Emsur, part of Grupo Lantero, help companies to protect cheese, improve

PPWR is a data challenge. In this Spotlight, we find out how Centric Software® tackles the challenge through a connected

In this Spotlight, Plastipak discusses the opening of its PET material centre in Verbania, Italy. Home to pakPET™ Single Pellet

In the latest edition of the Spotlight, Matthew Wright, Founder and CEO of FOREST-PKG, shares why finding the right

Duynie has decades of experience in developing applications for side-stream potato starch. With Novinexx CPB, the company is applying


In this edition of The Spotlight, Markem-Imaje examines how 2D coding is redefining the role of flexible packaging and
As PET bottles incorporate more recycled content, become lighter and adopt label constructions, the adhesive securing the label must perform

In this edition of The Brief, we’re trying something a bit different – I’m reflecting on the stories we’

Z1RO has been nominated as a finalist in the Start-Up New Materials category of the 2026 Sustainability Awards. The


OPACKGROUP and Morssinkhof-Rymoplast have applied a 50%+ post-consumer recycled stretch sleeve to a recycled PET bottle and cap